

Armed Forces CGT: Job-Related Accommodation Relief
Job-related accommodation may protect your home from Capital Gains Tax. Learn how Private Residence Relief can apply to armed forces and key workers in the UK.
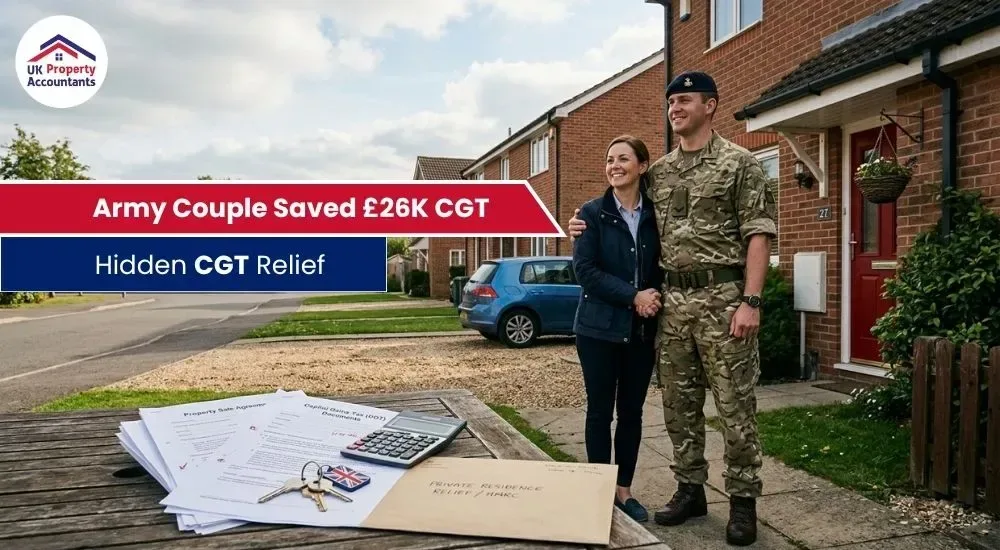
How an Army couple was one signature away from overpaying HMRC by tens of thousands — and why forces families, police officers, prison staff and thousands of other key workers across the UK could be sitting on the very same hidden relief.
A Quiet Completion. A Brown Envelope. A £26,000 shock — almost.
The Yorkes did everything right.
He served. She followed. For nine years they were posted the length and breadth of the UK, living in whichever set of Service Family Accommodation the Army handed them. All the while, their real home — the little house he had bought before they were married — sat quietly rented out, waiting for the posting that would bring them home.
That posting never came. Last year they sold.
The gain on paper: just over £55,000 each. The Capital Gains Tax bill any high-street calculator would spit out at 24%: over £13,000 each. Nearly £26,000 between them.
The bill they actually paid: £0. Each.
The difference between those two numbers was not luck. It was one subsection of one Act — and a conversation almost every property seller in a uniformed profession has never been told to have.
The Facts — a family home, a Queen's commission, & nine years on the road
Capt. Yorke bought the property before the marriage and lived there as his only home. Three years in, he married Mrs. Yorke. Almost immediately, his employer — the British Army — moved him into Service Family Accommodation. He had no choice. Mrs. Yorke moved with him.
For the next nine years they were posted all over the country. Somewhere along the way Mrs. Yorke was added to the title of the house. Neither of them lived in it again. They let it out, always intending to move back the moment a posting brought them close enough.
It never did. Two disposals. Two gains each over £55,000. On the face of it, two CGT bills.
Why Capt. Yorke's bill was Zero — the statute that does the heavy lifting
Principal Private Residence Relief lives in TCGA 1992 s.222 and s.223. Live somewhere as your only or main residence for the whole time you own it and the gain is fully relieved. Live there for part of the time and you get a time-apportioned share.
Capt. Yorke actually lived in the property for the first three years. Textbook s.222.
The other nine years are where most advisers stop reading — and where TCGA 1992 s.222(8A) quietly does the heavy lifting. That subsection defines "job-related accommodation", and s.222(8) then treats the entire time an owner spends in it as if they were living in their own home — with no time limit — provided they still intend to move back in due course.
Service Family Accommodation issued to a serving member of the armed forces is the textbook example. HMRC confirm it themselves at CG64555 and CG64465. No four-year cap. No obligation to physically move back in. Just a genuine intention — which Capt. Yorke held right up to the day the "For Sale" sign went up.
Add the final nine months of ownership, which s.223(2) exempts in any event once a property has qualified as a main residence at any point, and every single month of Capt. Yorke's ownership is relieved.
Tax due: £0.
Mrs. Yorke's escape — & how close she came to a £13,000 bill she never saw coming
This is the part that keeps practitioners up at night.
Mrs. Yorke never actually set foot in the property as an owner. She only went on the title after she was already living in Service family Accommodation. Read s.222 the way most people read it — "a dwelling which is, or has at any time in his period of ownership been, his only or main residence" — and she has a serious problem. A house you have never lived in as an owner is not, on its face, your residence.
But s.222(8) does not demand that you occupied the property before the job-related accommodation began. It asks a different question: are you living in job-related accommodation, and is there a dwelling you intend to occupy as your only or main residence? HMRC confirm at CG64465 that this can extend to a dwelling the owner intends to occupy in due course — including where the job-related accommodation arises through a spouse's employment.
That was Mrs. Yorke's lifeline. The Service Family Accommodation was there because of her husband's service. The house was the only property the couple owned and the one they intended to move into if the Army ever posted them close enough. On those facts, s.222(8) delivers deemed occupation for the whole of her ownership period. Add the final nine months. The gain is fully relieved.
Tax due: £0.
What would have happened if the analysis had gone the other way
Had s.222(8) been rejected for Mrs. Yorke — perhaps because HMRC pushed back on whether a property she had never physically occupied could truly be a residence she intended to occupy — the only fallback is the four-year employment absence rule in s.223(3). And that rule demands actual occupation before and (broadly) after the absence. Mrs. Yorke has neither.
She would have been left staring at over £55,000 of chargeable gain, a CGT bill of over £13,000 at 24%, a 60-day CGT return, and interest and penalties if the return had gone in on the wrong footing.
And Capt. Yorke? If a well-meaning generalist had simply reached for the four-year rule — the one every non-specialist half-remembers from their exams — he would have relieved only the first 36 months of actual occupation, 48 months of deemed occupation, and the final 9 months. His CGT bill would have been just under £5,000.
The couple would have thanked their adviser. They would have thought it was a good result. And they would have paid tax that was never due.
If you wear one of these uniforms, this could be you
Job-related accommodation is nowhere near as niche as most people think. Any of the following can qualify, and any of them could be sitting on a PRR position dramatically better than the one an off-the-shelf CGT calculator will give them:
- Serving members of the Army, Royal Navy and RAF living in Service Family Accommodation.
- Police officers required to live in police-provided housing.
- Prison officers and prison governors in tied accommodation.
- Boarding-school teachers and matrons living on-site.
- Publicans and pub managers living above the pub.
- Tied-cottage agricultural workers.
- Ministers of religion in manses and vicarages.
- Any employee where the accommodation is required for the proper performance of duties, is customary and provided for better performance, or is required for security.
If your employer requires you to live somewhere specific, ask whether s.222(8A) applies before you sell. Not after.
Three lessons every property owner should take from this
1. Job-related accommodation is not just for the armed forces.
It reaches into policing, the prison service, agriculture, education, hospitality and the clergy. If your job dictates where you sleep at night, the tax treatment of the home you own elsewhere is almost certainly not what the internet tells you it is.
2. The four-year employment absence rule is not the only route to relief — often not the best one.
It is simply the route most people have heard of. Job-related accommodation under s.222(8) has no time limit. Getting the right subsection can be the difference between a five-figure tax bill and no tax bill at all.
3. Voluntary reporting is a strategy, not a formality.
The Yorkes filed 60-day CGT returns even though no tax was due. That puts the PRR position on HMRC’s system, closes the enquiry window on the correct footing, and protects them if the file is ever picked up years later. On material disposals where a strong relief is being claimed, voluntary reporting is very often the right call.
What this means for you — & why the clock is already ticking
If you are a serving member of the armed forces, a police officer, a prison officer or any employee living in accommodation your employer requires you to occupy — and you own a property elsewhere that you have let out or left empty — you may be sitting on a Principal Private Residence Relief position that is significantly better than you think.
If you are a landlord or property investor and your sale involves any period of non-occupation, the analysis is very rarely as simple as "it wasn't my home, so it's all taxable". Deemed occupation reliefs, the final period exemption and the residual form of lettings relief that survived April 2020 are all live questions.
If you are already under contract, or expect to complete within the next twelve months, the time to get the analysis done is now — not after completion, when the 60-day return clock is already running down.
How UKPA Can Help?
We are a chartered firm specialising in UK property taxation. We prepare CGT computations, run the full PRR analysis, file 60-day CGT returns and — where appropriate — make the technical case to HMRC in the return itself, so the relief position is on record from day one.
Contact usIf you would like us to review your position before you sell:
Email: contact@ukpa.co.uk
Website: ukpa.co.uk
This article is based on a real client engagement. Names, dates and identifying details have been changed. It is written for general information and does not constitute tax advice. The application of TCGA 1992 s.222 to any specific disposal depends on the full facts and should be reviewed by a qualified adviser before you rely on it.
About the author
UK Property Accountants is a specialist property tax and accounting firm serving clients across the UK and abroad. With over 10,000 properties under active accounting management, £8 billion in assets under accounting, clients spanning 57 countries, and an expert team of ACCAs and CTAs, we bring a depth of real-world property tax experience rarely found in any single firm. We hold a 99% client satisfaction rate and an Excellent rating on Trustpilot. All published content is reviewed by qualified professionals in line with current HMRC guidance.
Introducing RentalBux: Our MTD Software for Landlords
Generic software doesn’t understand property businesses and requires manual intervention to meet deadlines. That’s why we developed RentalBux!
- Built by Property Experts
- Designed for UK Landlords
- HMRC Recognised and MTD Compliant

Confused Where To Start?
Schedule a Free 15-minute discovery call by providing your contact details, mentioning your requirements, and selecting a convenient date for the call.
How our discovery call works:
- Complete Our Contact Form
- Discovery Calls Scheduled
- Receive a Tailored Proposal