
SDLT Relief on Probate Property
Stamp Duty (SDLT) Relief for Probate Properties
Probate Relief is governed under Schedule 6A of the Finance Act 2003. You may qualify for the Stamp Duty Relief on Probate Properties, if you are a trader acquiring or have acquired a Probate Property directly from the deceased's representatives.
Excellent 500+ reviews on

Get Probate Relief Right
Why Choose UKPA for Stamp Duty Relief on Probate Properties?
When it comes to claiming SDLT relief on probate properties experience matters, at UK Property Accountants, we bring expert guidance to full claim management; here's what sets our service apart.
Probate Property Relief Experts
We stay current with HMRC's evolving guidance on probate property claims, ensuring you benefit from the correct tax treatment and optimise SDLT savings.
Tailored Advice
Our advice isn't generic. We take the time to understand your probate purchase and give advice that's relevant, reliable, & backed by legislation.
Comprehensive Services
From checking eligibility and preparing reports to dealing directly with HMRC, we manage the entire process to ensure you get the SDLT relief you're entitled to.
What our clients say about us
Testimonials
Rendering the best service with a team of qualified and regulated accountants and tax advisers.
Understanding Probate Relief
What is Probate Relief?
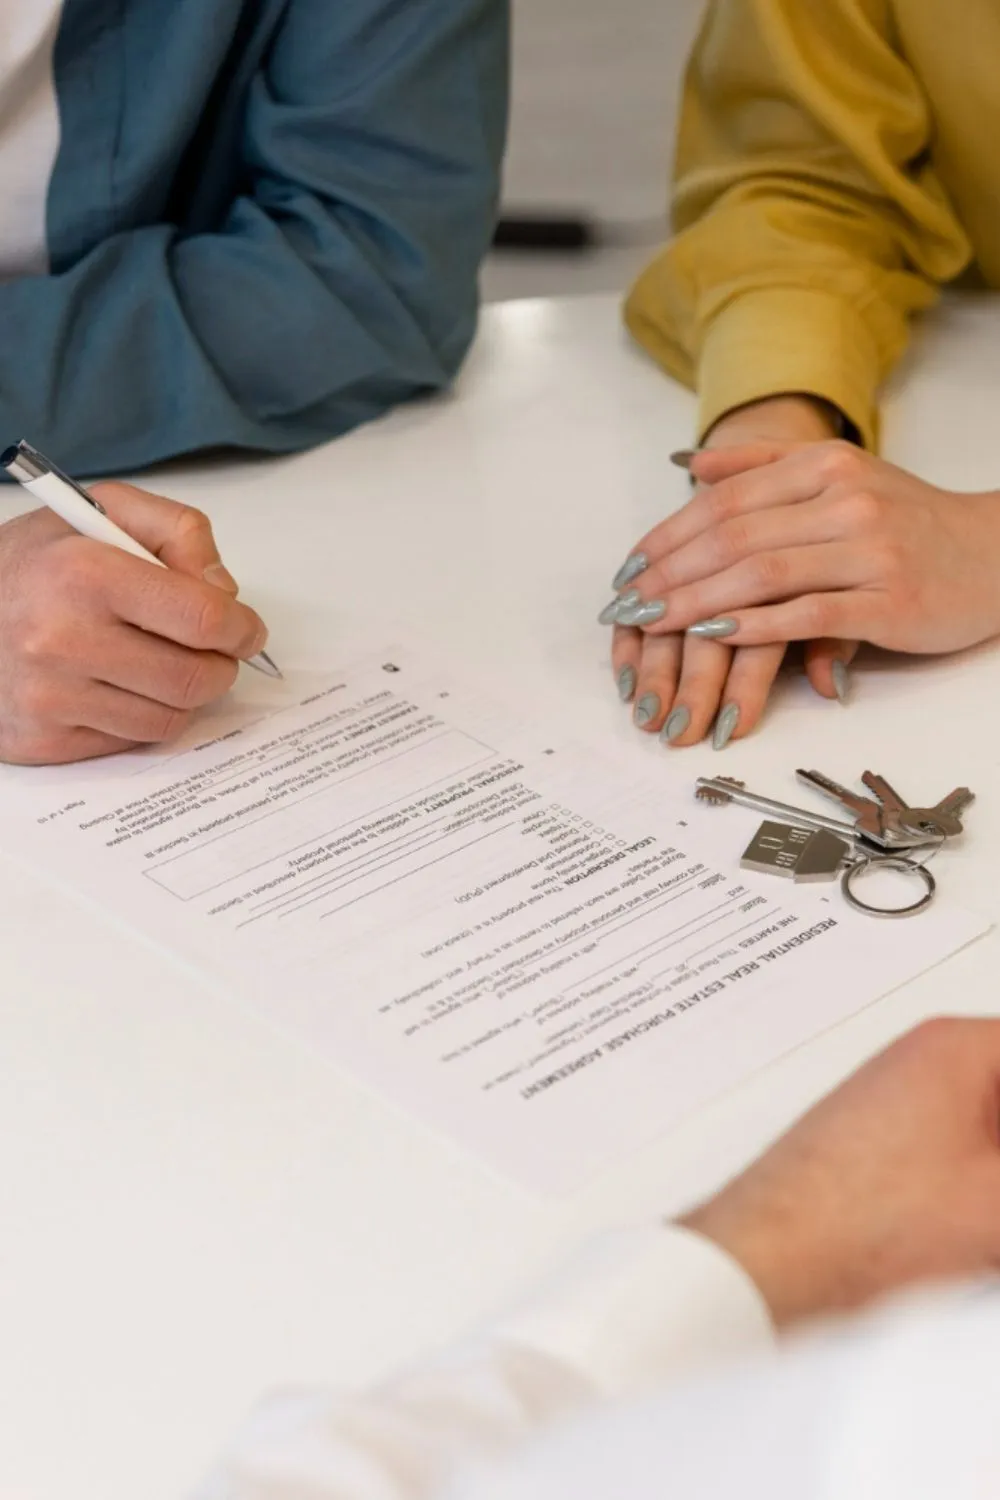
When a property trader, meaning a company, a limited liability partnership, or a partnership whose members are all either companies or limited liability partnerships, that carries on the business of buying and selling dwellings purchases a dwelling from a personal representative of the deceased person, the transaction may qualify for probate relief.
This stamp duty relief on probate properties provides for either full or partial exemption from SDLT, depending on compliance with the specific statutory criteria set out within the legislation.
Specific conditions where the Probate Relief is applicable:
- The acquirer must be a Property Trading Company.
- The acquisition must be of a dwelling acquired from the personal representatives of the deceased.
- The deceased must have resided in the dwelling as their only or main residence at some time in the two years preceding their death.
- The transaction must have occurred within the Property Trader's ordinary course of business.
- The Property Trader must adhere to post-acquisition restrictions. These include a prohibition on exceeding prescribed expenditure thresholds for refurbishment, refraining from leasing or licensing the dwelling, and preventing occupation by the trader's principals, employees, or connected parties; otherwise, it is subject to clawback.
- The total land area acquired must not surpass the "permitted area" (0.5 hectares).
What We Offer
Optimising Stamp Duty Relief on Probate Properties
At UK Property Accountants, we help property traders make the most of SDLT reliefs when buying from estates. From reviewing eligibility to securing refunds, our tailored service ensures no opportunity is left behind. We'll tell you if your transaction qualifies and, just as importantly, if it doesn't.
Written Tax Advice
Our written tax advice offers a comprehensive review of the purchasing company's nature and property purchase details, supported by in-depth research and expert analysis.
Once all necessary details are gathered, our tax advisor prepares a detailed, well reasoned report explaining whether your transaction qualifies for the relief.Refund Claims from HMRC
Does the Probate Relief apply to any of your previous transactions? Our team can assess your situation, determine your potential eligibility, and identify any overpayments based on the transaction's nature and completion date. We guide you through the complex reclaim process, and liaise directly with HMRC on your behalf to help you recover the amount you are entitled to.
Our Process
How We Work
At our core, we place great emphasis on trust and confidentiality. Our top priority is to ensure that you feel reassured, heard, and valued. We provide unwavering support, understanding, attentive listening, a structured approach, and extensive expertise as a cohesive team. By addressing urgent needs while taking the time to understand you, we foster trustworthy and dependable relationships.
Pre-Transaction
Initial Assessment
We review the information you provide to assess the potential Probate Relief claim and determine whether you qualify for the relief.
Engage with Us
We will send you a proposal and/or engagement letter outlining our services and associated fees.
Data Collection
After the engagement process, we will gather all necessary details to prepare the tax advice report and verify all relevant information.
Client Approval
After gathering the required information, we will draft a facts section and provide you with a draft of the advice report for your review and approval.
Tax Advice Report
After receiving confirmation from you regarding the draft facts, our tax advisor will prepare a detailed report forming our opinion based on the legislation requirement and your unique situation.
Dispatch of the Report
Once finalised, we will send you the completed report.
Post-Transaction
Initial Assessment
We review the information you provide to assess your potential Probate Relief claim and determine whether a claim can be made to the HMRC.
Engage with Us
We will send you a proposal and/or engagement letter outlining our services and associated fees.
Data Collection
If, after our initial assessment, we find that you are eligible, we will gather all necessary details to support your MDR claim.
Letter of Claim
We will prepare a detailed report outlining the grounds for your refund claim, explaining why the transaction qualifies for the stamp duty relief on probate properties, and calculating the SDLT due after applying the refund claim.
Client Approval
We will send you a draft of the letter of claim for you to review and approve before submitting it to HMRC.
Submission of the Letter to Revenue Scotland
Once you approve the facts in the drafted letter, we will submit it to HMRC with all required documentation.
Follow-Up
We will keep you informed every step of the way, providing updates on your claim's progress and any responses from HMRC. Rest assured, we will continue to follow up with the HMRC monitor until your refund is received.
Meet Our Experts
We are a team made up of people from all walks of life who share a common passion for simplifying complex tax property accounting and compliance for you.
Raju Gajurel is a qualified chartered accountant and chartered tax adviser with more than 22+ years’ experience in accounting, finance, and taxation.
View ProfileRaju Gajurel
CEO
Peter is a pragmatic, thoughtful and experienced property tax adviser and accountant who always strives to find the best solution for clients’ accounting and tax problems.
View ProfilePeter Kyprianou
VICE PRESIDENT
Runal is an experienced property tax adviser who specialises in company tax planning and VAT compliance, ensuring optimal solutions for diverse client needs.
View ProfileRunal Bhattarai
DIRECTOR OF TAX AND CLIENT SERVICES
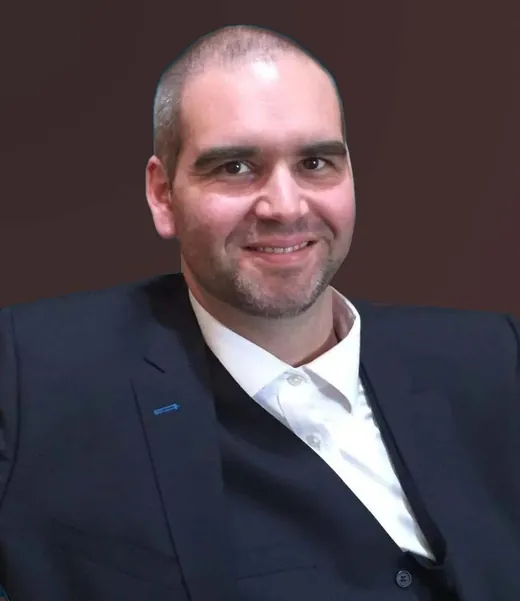
Richard, with exposure in aerospace, engineering, education, and finance sectors, thrives on providing effective analytical solutions for clients.
View ProfileRichard Paul Siddons
CHIEF EXPERIENCE OFFICER-CXO,CLIENT ADVISORY
Related Services
Our Comprehensive Services
We are committed to helping you achieve financial prosperity while optimising your tax position in the most effective and efficient way possible.
Stamp Duty & Land Taxes
SDLT Group Relief Claim
Missed out on SDLT Group Relief? Our experts assist you in claiming your relief efficiently, ensuring you pay only what you owe.
Learn More
Stamp Duty & Land Taxes
SDLT Return
Our team ensures accurate and timely submission, helping you stay compliant while minimising tax liabilities.
Learn More
Stamp Duty & Land Taxes
First Time Buyer's Relief
Buying your first home? We guide you through First-Time Buyers' Relief, ensuring you save on SDLT & keep more money in your pocket.
Learn More
Our Accounting & Tax Recipes
Latest News & Articles
Dive into our latest news & articles on property, finance and tax-related content.
Our Articles Covering SDLT Probate Relief
 2024 Stamp Duty Land Tax Changes: Key Updates ExplainedRead More
 Probate Property: Understanding the Key Tax ImplicationsRead More
 Inheriting a House in the UKRead More
Our Latest News on SDLT Probate Relief
FAQs
General queries by our clients related to Stamp Duty Relief for Probate Properties are answered here.
Who qualifies for Stamp Duty Relief for probate relief?
What conditions must be met to keep the SDLT relief?
How do I claim the SDLT relief?
What if I don't resell within 3 years?
Have more questions? Check out our Complete Guide for everything you need to know about Stamp Duty Relief for Probate Properties in one place.
Introducing RentalBux: Our MTD Software for Landlords
Generic software doesn’t understand property businesses and requires manual intervention to meet deadlines. That’s why we developed RentalBux!
- Built by Property Experts
- Designed for UK Landlords
- HMRC Recognised and MTD Compliant

Confused Where To Start?
Schedule a Free 15-minute discovery call by providing your contact details, mentioning your requirements, and selecting a convenient date for the call.
How our discovery call works:
- Complete Our Contact Form
- Discovery Calls Scheduled
- Receive a Tailored Proposal