
ATED Advice for Companies Owning UK Residential Property
ATED Return Preparation & Advice from Property Accountants
ATED applies to certain companies, partnerships with corporate members and collective investment schemes that own UK residential property above £500,000. We advise on whether it applies to you and on reliefs and, where you appoint us, prepare and submit your ATED return as your agent.
Excellent 500+ reviews on

Loading form…
Our Speciality
Why Choose UK Property Accountants for ATED Support?
ATED is all about property. That is why you should trust a firm that specialises in UK property to submit ATED return. UK Property Accountants is that firm, delivering property-focused expertise to you and your businesses.
Relief Declaration Return
We advise on reliefs that may apply and, where you instruct us, prepare and submit a relief declaration return as your agent.
Compliance Support
We specialise in ATED compliance, offering professional advice tailored to your property ownership structure and your needs.
Property Valuation Support
We provide reliable and compliant property valuations to help you meet ATED requirements and maximise tax relief.
What our clients say about us
Testimonials
Rendering the best service with a team of qualified and regulated accountants and tax advisers.
Introduction to ATED
What is ATED & ATED Return Filing?
The Annual Tax on Enveloped Dwellings (ATED) is a tax applied to UK residential properties valued over £500,000 that are owned by non-natural persons, such as companies, partnerships with corporate members and collective investment schemes. The tax was introduced to discourage the practice of holding high-value residential properties within corporate structures to avoid other taxes. ATED charges are based on the property’s valuation band, with tax rates increasing according to the property's value.
An ATED return is an annual submission required by HMRC to report the ownership, use and valuation of a property to determine the tax liability. Even if no tax is due because of applicable reliefs, property owners must still file an ATED return to comply with HMRC regulations.
Even if no tax is due, it is a legal requirement to submit ATED return for eligible entities. Here are the key groups that must submit an ATED return to HMRC.
- Companies owning UK residential properties over £500,000
- Partnerships that include a corporate partner and hold qualifying properties
- Collective Investment Schemes if their assets exceed the threshold
- Businesses qualifying for reliefs that reduce ATED liability to zero must still submit a Relief Declaration Return
Do Not Miss the ATED Deadline!
Understanding ATED Penalties
What are Penalties for Late ATED Return Filing?
At UK Property Accountants, we advise ATED compliance and tax planning, ensuring that your returns are filed accurately and on time. Our expertise helps you avoid unnecessary penalties, protect your business assets, and remain fully compliant with HMRC regulations.
Late Filing Penalties
If an ATED return is made after the ATED submission deadline, HMRC charges a £100 penalty immediately, increasing to £10 per day (up to £900) after three months. At six months, an extra £300 or 5% of the tax due applies, with another £300 or 5% penalty at 12 months.
Late Payment Penalties
Late ATED tax payments incur a 5% penalty after 30 days, another 5% after six months, and an additional 5% after 12 months. Interest is also charged daily on unpaid amounts, increasing overall costs significantly. Paying on time is crucial to avoid these escalating penalties.
Severe Consequences for Inaccurate Return
The penalty percentage for inaccurate return is classified into one of six ranges ranging from 0% to 100%, determined by the nature of the behaviour and whether the disclosure was 'prompted' or 'unprompted'.
Why Us
Let UK Property Accountants Help You to Submit Your ATED Return
We at UK Property Accountants are committed to making the submission of ATED return process as simple and stress-free for you as possible. That’s why numerous clients have been trusting us with their ATED needs for years.
Penalty Assessment
We provide a comprehensive penalty assessment service by reviewing ATED non-compliance risks and helping clients understand potential penalties.
HMRC Appeal
We support clients in contesting unfair ATED penalties. Our experienced tax advisers provide representation for negotiating and potentially reducing HMRC penalties.
Voluntary ATED Disclosure
We assist clients in disclosing previously undeclared ATED taxes, ensuring full compliance with HMRC.
Record of Success
With a strong reputation and numerous satisfied clients behind, we can truly claim to be a leader in the field.
Our Process
How We Work
Our work is centred around efficiency, collaboration, and delivering exceptional results to our clients.
Initial Discovery Call
We start with a straightforward process. Answer a few simple questions to help us understand your circumstances. It’s hassle-free, quick and designed to save you time.
Data Gathering & Analysis
Once we have the details, our team of experienced accountants gets to work. You can trust us to manage the complexities and ensure everything is accurate and compliant.
Thorough Review & Timely Submission
We conduct a meticulous review to ensure accuracy, compliance, and completeness in every submission. Our streamlined process guarantees timely submissions, so you never miss a deadline.
Ongoing Support
Our commitment extends beyond accounting and tax advisory work. We provide ongoing support, including tax planning and addressing accounting queries throughout the year.
What Our Clients Say
Hear directly from our clients about their experiences, results, and why they trust us with their property tax needs.
UKPA provided exceptional support with our ATED filings, successfully appealing additional HMRC charges. Their expertise and proactive approach reduced our penalty by £5,400, lowering our total liability to £35,092.08. Professional, detail-oriented, and highly effective—highly recommended for ATED matters.
UKPA’s expertise and persistence in handling our ATED case led to HMRC proposing a charge reduction and a total refund of £16,520 for our two companies. Their clear communication and proactive approach ensured the best outcome. Highly recommended for ATED matters
Meet Our Experts
We are a team made up of people from all walks of life who share a common passion for simplifying complex tax property accounting and compliance for you.
Raju Gajurel is a qualified chartered accountant and chartered tax adviser with more than 22+ years’ experience in accounting, finance, and taxation.
View ProfileRaju Gajurel
CEO
Peter is a pragmatic, thoughtful and experienced property tax adviser and accountant who always strives to find the best solution for clients’ accounting and tax problems.
View ProfilePeter Kyprianou
VICE PRESIDENT
Runal is an experienced property tax adviser who specialises in company tax planning and VAT compliance, ensuring optimal solutions for diverse client needs.
View ProfileRunal Bhattarai
DIRECTOR OF TAX AND CLIENT SERVICES
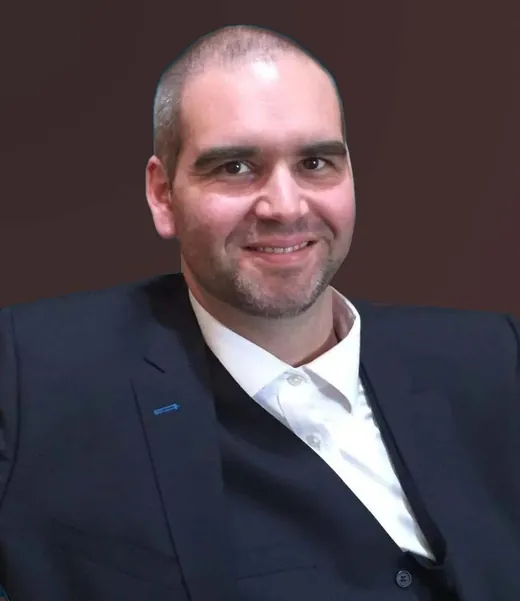
Richard, with exposure in aerospace, engineering, education, and finance sectors, thrives on providing effective analytical solutions for clients.
View ProfileRichard Paul Siddons
CHIEF EXPERIENCE OFFICER-CXO,
CLIENT ADVISORY
Your Complete ATED Resource Hub
From accurate tax estimates to in-depth knowledge, our calculator and eBook are here to support you in every step of your Annual Tax on Enveloped Dwellings journey.
Effortless ATED Calculation
We’ve designed an ATED Calculator to help you estimate your annual charge based on your property value and ownership structure. It’s quick, simple, and built specifically for companies owning UK residential properties.
Calculate Your TaxesDownload Our Free eBook on ATED
Confused about ATED? Our free ebook simplifies it all. Get clear, step-by-step guidance to understand your obligations and avoid costly mistakes. Stay compliant and save time with expert-backed insights.
Download eBook
Related Services
Our Comprehensive Services
We are committed to helping you achieve financial prosperity while optimising your tax position in the most effective and efficient way possible.
Accounts & Tax Return
Company Accounts & Tax Return
Need help with Self Assessment Tax Returns? Our expert team ensures you meet the HMRC deadline without hassles.
Learn More
Accounts & Tax Return
Annual Update: ROE
We handle everything, ensuring your capital gains tax is accurately calculated while keeping you compliant and stress-free.
Learn More
Accounts & Tax Return
De-enveloping UK Property
Navigating non-resident capital gains tax can be complex, but we make it simple. Stay compliant without the stress—we handle it all for you.
Learn More
Our Accounting & Tax Recipes
Latest News & Articles
Dive into our latest news & articles on property, finance and tax-related content.
 How to file your Annual Tax on Enveloped Dwellings | ATED ReturnRead More
 Reliefs Under Annual Tax on Enveloped DwellingsRead More
 ATED Return Amendment Guide: When & How | Tax TipsRead More
 Understanding ATED Valuation RulesRead More
 Voluntary ATED Compliance: A Guide for Overseas CompaniesRead More
 ATED Relief for Related Persons and Market Rent: A Complete GuideRead More
FAQs
General queries by our clients related to submitting ATED return are answered here.
Can I claim a refund of ATED if I sell my property?
How to pay ATED charges?
A trust of which I am a beneficiary owns property in the UK which is probably worth more than £500k. The property is rented out on a commercial basis. Do I need to submit ATED return?
Can I appeal an ATED decision made by HMRC?
I am a director of a company which is not incorporated or resident in the UK but owns land in the UK. Is the company subject to ATED provision?
My company beneficially owns 10% of a single dwelling interest. The single dwelling interest as a whole is worth £10 million. How much is the company liable for ATED?
If my property value changes, what happens?
Have more questions? Check out our Complete Guide for everything you need to know about submitting ATED return in one place.
Introducing RentalBux: Our MTD Software for Landlords
Generic software doesn’t understand property businesses and requires manual intervention to meet deadlines. That’s why we developed RentalBux!
- Built by Property Experts
- Designed for UK Landlords
- HMRC Recognised and MTD Compliant

Confused Where To Start?
Schedule a Free 15-minute discovery call by providing your contact details, mentioning your requirements, and selecting a convenient date for the call.
How our discovery call works:
- Complete Our Contact Form
- Discovery Calls Scheduled
- Receive a Tailored Proposal