

Stamp Duty on Mixed-Use Property
Discover common pitfalls and challenges related to stamp duty on mixed-use properties and how to overcome them.
In this blog post, we will delve into the topic of Stamp Duty Land Tax (SDLT) on mixed-use properties, offering valuable insights for tax advisers and business owners alike. Let’s start with the basics.
Understanding Mixed-Use Properties
Mixed-use properties refer to properties that encompass both residential and non-residential components. These can include combinations such as a flat connected to a shop, doctor’s surgery or office space.
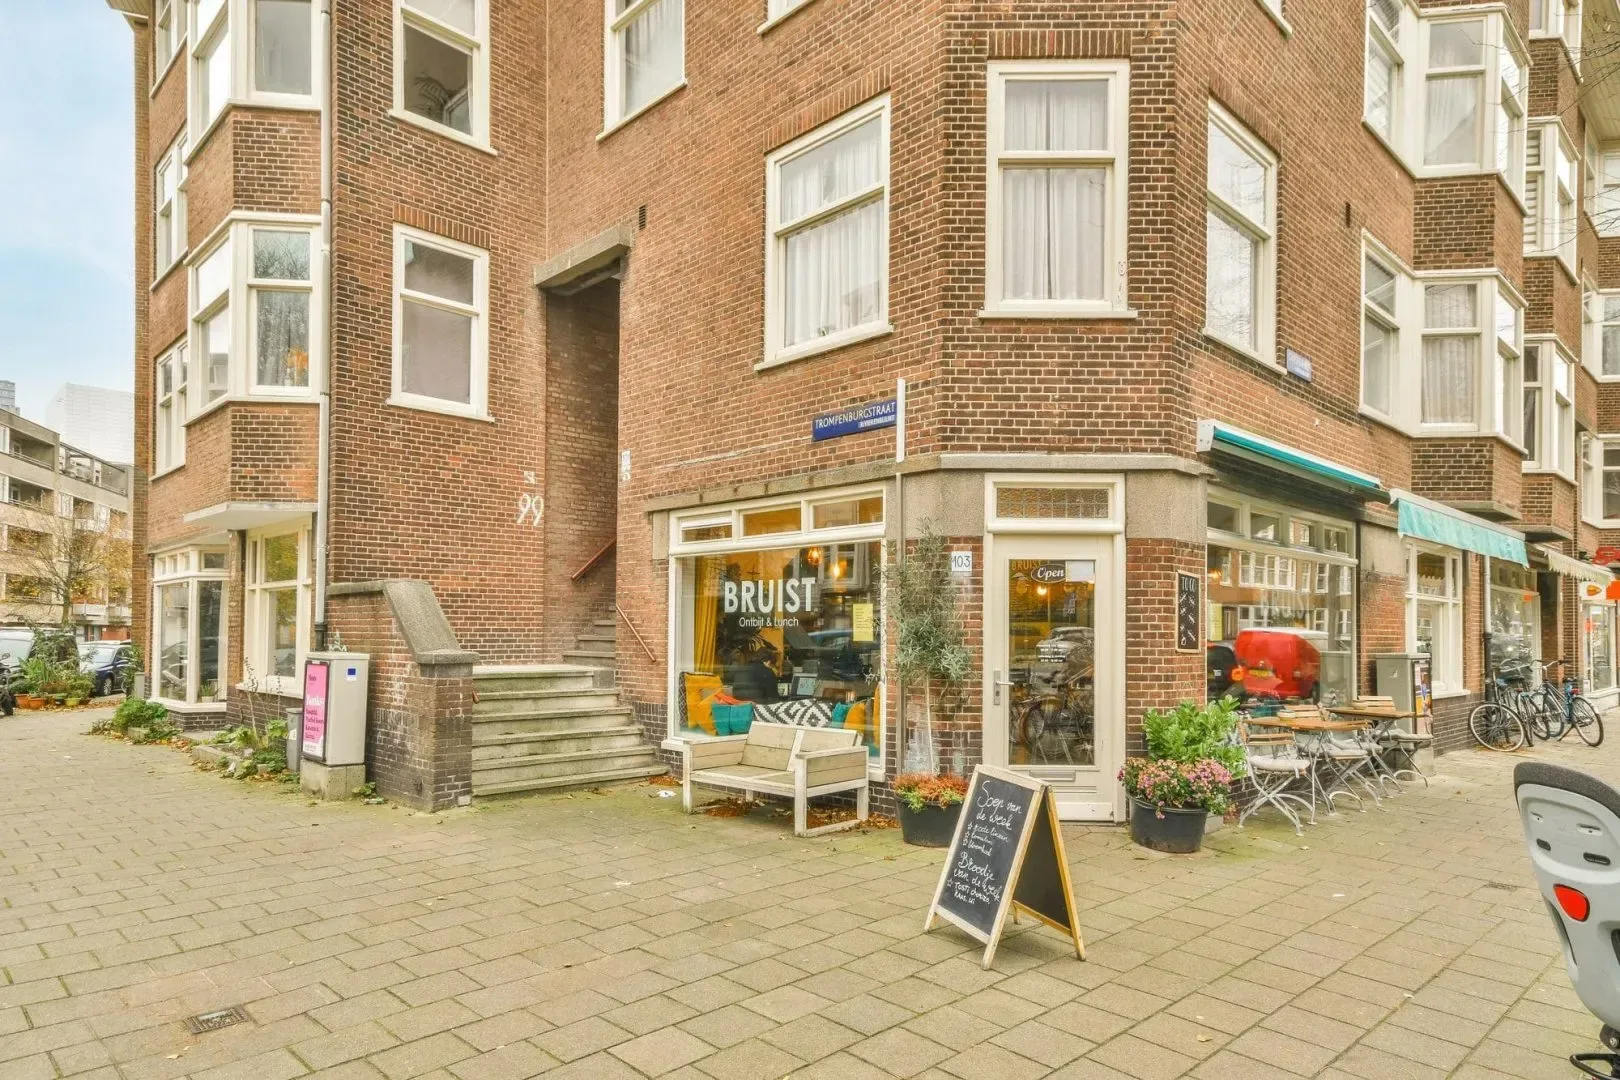
Essentially, a mixed-use property combines commercial and residential aspects within a single premises. To illustrate, imagine a building with residential flats occupying the upper floors and a bustling coffee shop operating on the ground floor.
An Introduction to SDLT on Mixed-Use Properties
When it comes to purchasing non-residential or mixed-use land or property, Stamp Duty Land Tax (SDLT) is applied to progressively higher portions of the property price, specifically when the payment exceeds £150,000.
It’s important to note that these rates and thresholds may differ for residential properties or in specific circumstances. Therefore, it is recommended to consult the official guidelines or seek professional advice when considering the purchase of non-residential or mixed-use land or property to understand the applicable SDLT rates and thresholds accurately.
SDLT Rates for Mixed-Use Property
Determining whether a property qualifies as residential or not is a straightforward “all or nothing” process. You don’t need to worry about dividing the consideration between the residential and non-residential aspects of the property. Before Multiple Dwellings Relief was abolished for transactions with an effective date on or after 1 June 2024, the exception was where it came into play; in such cases, consideration was limited to the apportioned value allocated to the dwellings.
Where a transaction includes land that is not residential property, it is “mixed-use”, so the following rates apply:
| Portion of the consideration | SDLT Rate |
|---|---|
| Up to £150,000 | 0% |
| The next £100,000 (the portion from £150,001 to £250,000) | 2% |
| The remaining amount (the portion above £250,000) | 5% |
HMRC Guidance on Mixed-Use Property
The HMRC manual pages for mixed-use property are SDLTM00390 and SDLTM00395. These manuals provide technical guidance but may not offer definitive answers in every case.
How Claims Work for Mixed-Use Property
If you are purchasing a mixed-use property, you need to complete the SDLT1 form, selecting code 02 under “type of property”. Additionally, you must fill out form SDLT4, which can be found by visiting the HMRC site.
Can I Claim Multiple Dwellings Relief (MDR) on a Mixed-Use Property?
Multiple Dwellings Relief was abolished for transactions with an effective date on or after 1 June 2024, so it is no longer available on a mixed-use purchase unless transitional rules apply (broadly, where contracts were exchanged on or before 6 March 2024).
Where MDR could be claimed, it applied only to the residential part of the transaction. For the non-residential portion, normal non-residential rates applied. It was essential to apportion the consideration between the residential and non-residential portions. For the residential part where MDR applied, the residential SDLT rate had to be applied.
Conclusion
In conclusion, understanding Stamp Duty Land Tax (SDLT) on mixed-use properties is crucial for tax advisers and business owners. By grasping the classification of mixed-use properties and the corresponding SDLT rates, you can navigate the tax landscape with confidence.
Remember to consult the HMRC manuals for specific guidance, complete the necessary forms accurately and check whether the Multiple Dwellings Relief (MDR) transitional rules apply to your transaction. Stay informed about the latest SDLT rates and regulations to ensure compliance and make informed financial decisions.
Take control of your tax planning today and consult with our experienced tax advisers to ensure you make the most of your mixed-use property investments.
Contact us now to schedule a quick initial Discovery Call and explore the possibilities!
About the author
UK Property Accountants is a specialist property tax and accounting firm serving clients across the UK and abroad. With over 10,000 properties under active accounting management, £8 billion in assets under accounting, clients spanning 57 countries, and an expert team of ACCAs and CTAs, we bring a depth of real-world property tax experience rarely found in any single firm. We hold a 99% client satisfaction rate and an Excellent rating on Trustpilot. All published content is reviewed by qualified professionals in line with current HMRC guidance.
Introducing RentalBux: Our MTD Software for Landlords
Generic software doesn’t understand property businesses and requires manual intervention to meet deadlines. That’s why we developed RentalBux!
- Built by Property Experts
- Designed for UK Landlords
- HMRC Recognised and MTD Compliant

Confused Where To Start?
Schedule a Free 15-minute discovery call by providing your contact details, mentioning your requirements, and selecting a convenient date for the call.
How our discovery call works:
- Complete Our Contact Form
- Discovery Calls Scheduled
- Receive a Tailored Proposal